The Greeks Request
The purpose of the greeks request is to provide greek information from a specific option instrument, based on the greek settings used in the request.
The greeks format
The greeks request must be formed by the option instrument symbol and the greek definition. These are separated by the exclamation mark ‘!’, while the greek definition must be enclosed in single quotation marks ‘’. The easiest way to add the greeks requests, is to go to the Advanced Options frame populated with the desired options and from its menu, select Copy to Clipboard and paste it to Excel.
OPTION_SYMBOL!'GREEK_DEFINITION'
The OPTION_SYMBOL parameter is the option instrument symbol used in QST.
Note
For option instruments, you can either use the actual symbol of the option, e.g. EWZ26C3400 (E-mini S&P End of Month options), or using the underlying symbol instead, e.g. ESZ26{EW}C3400. Only one option instrument and greek definition can be used per greeks request.
1. Greeks (Delta, Gamma, Rho, Theta, Vega):
Field_Type#v2@Greek_Model@Underlying_Price@Volatility@Rate_of_Interest
2. Fair Value
Field_Type#v2@Greek_Model@Underlying_Price@Volatility@Rate_of_Interest@Fair_Value_Price_Format
3. Volatility
Field_Type#v2@Greek_Model@Underlying_Price@Option_Price@Rate_of_Interest
Note
The #v2 stands for the version 2 of the greeks request. You can access the documentation for the legacy version at this link.
The parameters composing the greek definition are explained below:
Field_Type - the main field requested, can be a greek parameter, fair value or volatility. Possible values:
DL – Delta
GM – Gamma
RH – RHO
TH – Theta
VG – Vega
FV – Fair Value
FVC - Custom Fair Value
Volatility – Implied Volatility
Greek_Model - computation model for the volatility, and in turn for all the greek values. Possible values:
Black-Scholes
Black76
Binominal
Trinominal
Barone-Adesi-Whaley
Bjerksund-Stensland02
Bachelier
Underlying_Price - provide the source for the underlying price that is used for the computation of the volatility, greeks and fair value. Possible values:
undST - uses the settlement price of the underlying future
undLS - uses the current price of the underlying future in the following order: arithmetic mean of the bid and ask, if one is missing it will try the other value, if both are missing it will use the Last / Previous Settlement price
custom price - add any custom price value in the format of the underlying
Note
undST can be used strictly for the computation of the volatility, it doesn’t affect greeks or fair value which can use undLS or a custom value.
Option_Price - provide the source for the option price that is used for the computation of the volatility. Possible values:
optST - uses the settlement price of the option
undLS - uses the current price of the option in this order: arithmetic mean of the bid and ask, if one is missing it will try the other value, if both are missing it will use the Last / Previous Settlement price
custom price - add any custom price value in the format of the option
Volatility - used for the computation of the greeks and fair value. Possible values:
volIMP or volIMPST - computes the volatility based on the settlement values of the underlying and option (undST, optST)
volIMPLS - computes the volatility based on the current price values of the underlying and option (undLS, optLS)
custom volatility - add any custom volatility
Rate_of_Interest - used for the computation of the volatility, greeks and fair value. Possible values:
roiIMP - uses the implied rate of interest
custom ROI - add any custom rate of interest
Fair_Value_Price_Format - determines what price format to use for the Fair Value fields. Possible values:
fvDEC - uses decimal format (it ignores legacy PFI’s with ^ notation)
fvUND - uses the format from the Last value of the underlying
Examples of greeks request
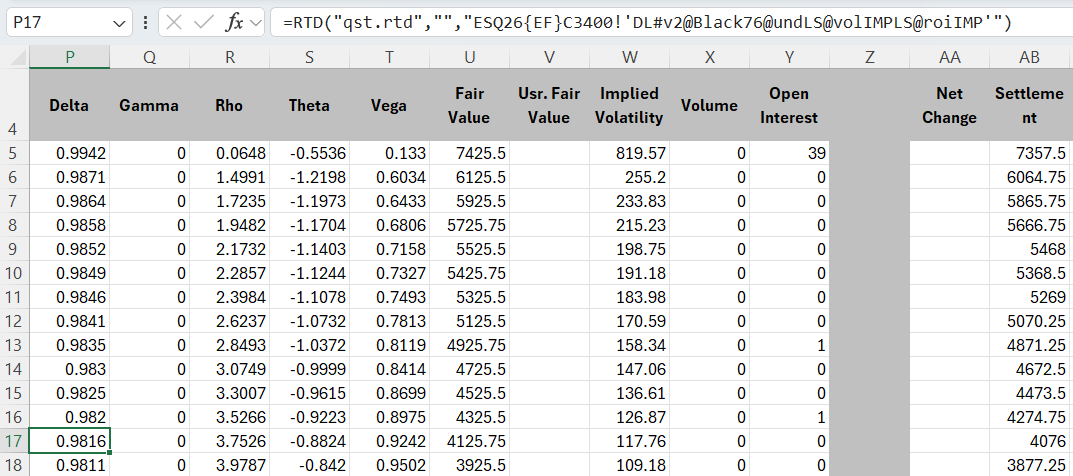
Requesting the Delta greek value for ESQ26{EF}C3400:
=RTD("qst.rtd","","ESQ26{EF}C3400!'DL#v2@Black76@undLS@volIMPLS@roiIMP'")
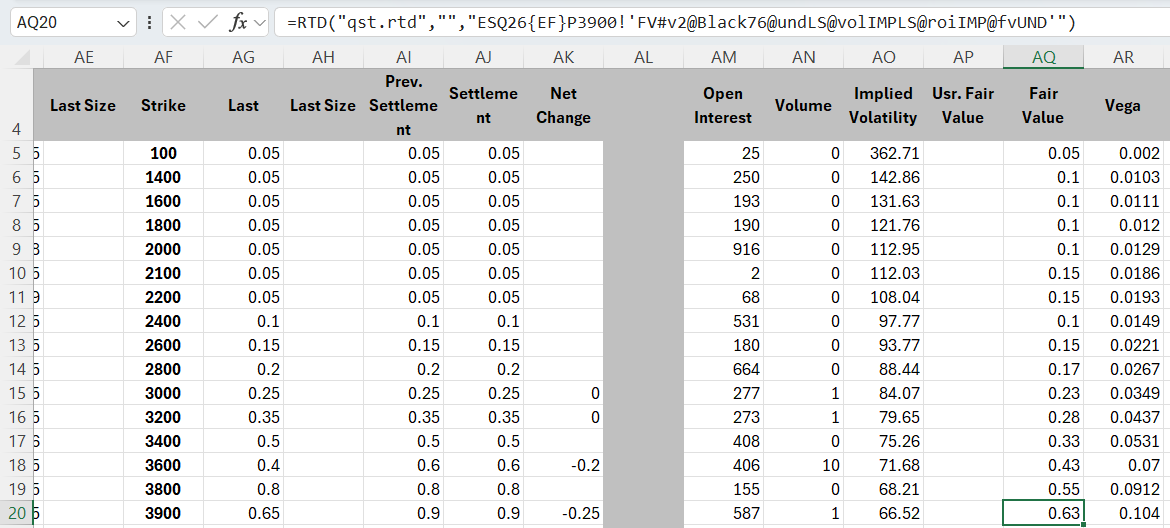
Requesting the Fair Value for ESQ26{EF}P3900:
=RTD("qst.rtd","","ESQ26{EF}P3900!'FV#v2@Black76@undLS@volIMPLS@roiIMP@fvUND'")
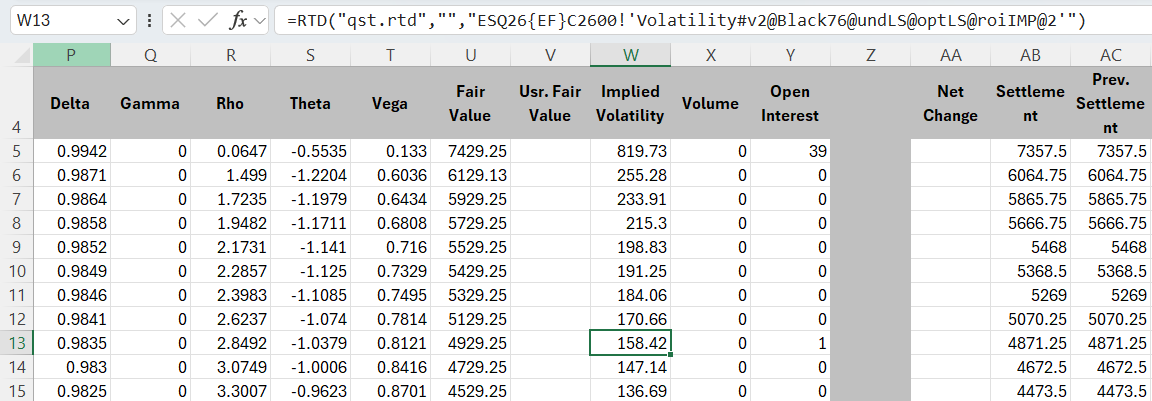
Requesting the implied volatility for EGCZ20{A}P1865:
=RTD("qst.rtd","","ESQ26{EF}C2600!'Volatility#v2@Black76@undLS@optLS@roiIMP@2'")